Elemental sulfur in agriculture: fertilizer, granules, price and uses

Soufre élémentaire jaune destiné aux fabricants d'engrais et d'acide sulfurique, E-Station
Soufre élémentaire agriculture : granulés et poudre de soufre jaune pour engrais et acide sulfurique, par E-Station

Agronomy · Sulfur

Elemental sulfur in agriculture: fertilizer, granules, prices and uses

Insoluble in water, elemental sulfur must be oxidised by soil bacteria before it can feed a plant. Particle size, temperature, forms and prices: the key points for using it well.

Request a quotation →

A bag of agricultural elemental sulfur shows 90 or 99% sulfur, far more than ammonium sulfate. Yet spread in March on yellowing rapeseed, it will change nothing before summer. Understanding why lets you buy it at the right time, in the right form and at the right price.

Elemental sulfur is sulfur as a pure element, the yellow solid recovered from refineries and gas processing plants, then sold as granules, pastilles, crushed lumps or powder. We describe this raw material on our page on sulfur trading, and in ground or coated form it also becomes a fertilizer in its own right.

According to World Fertilizer, global demand exceeded 71 million tonnes in 2024, 60% of it for fertilizers, mostly after conversion into sulfuric acid. This article covers the other route, agricultural elemental sulfur used directly in the field, before returning to the industrial logic that sets its price.

Agricultural elemental sulfur: what are we talking about?

In the soil, plants absorb sulfur in only one form, the sulfate ion. Elemental sulfur is insoluble in water. The manufacturer Hélinove sums up the consequence on its product sheet: elemental sulfur stays in the soil and oxidises gradually until it is converted into sulfates. This slowness is both its weakness, when the crop needs sulfur straight away, and its strength, when the aim is to rebuild a reserve that will not be washed away by winter rain.

Agricultural elemental sulfur: conversion into sulfate in the soil

The reference review by Germida and Janzen, published in Nutrient Cycling in Agroecosystems, establishes that the oxidation of elemental sulfur in soil is carried out mainly by micro-organisms, bacteria and fungi, and that temperature, water potential and aeration are the main constraints. The authors also note that a previous application of elemental sulfur often speeds up oxidation by stimulating the populations that live on it, and that reducing particle size favours the reaction.

The American magazine Organic Grower puts this into practice for agricultural elemental sulfur: for 99.5% pure sulfur in coarse particles, oxidation takes months, or even a year or more, with an optimum soil temperature between 24 and 38 °C and moisture slightly below field capacity.

Agricultural elemental sulfur: when it fits and when sulfate is needed

The deciding factor is how quickly the crop needs it. On rapeseed, Terres Inovia recommends 75 kg of SO3 per hectare in sulfate form at the start of stem elongation, as noted by the Journal Paysan Breton, because uptake becomes intense within a few weeks from stage C2. We detail this reasoning in our article on sulfur on rapeseed. On cereals, the window is a little wider and Arvalis considers that sulfate, elemental sulfur and thiosulfate are equally effective when applied between the start and end of tillering, the choice depending on cost and the balance sought with other nutrients.

Rebuilding the soil reserve

TheFrench Academy of Agriculture puts sulfate leaching losses at around 50 kg of SO3 per hectare, varying widely with the soil and winter rainfall, and notes that atmospheric deposition has fallen to around 11 kg of SO3 per hectare, seven times less than thirty years ago. In this context, agricultural elemental sulfur applied in autumn or on a previous crop slowly feeds the soil's organic and sulfate pool without being leached in January.

Acidification and calcareous soils

The oxidation of one tonne of sulfur releases protons, which locally lowers the pH. In calcareous soil, common in the Maghreb and the Paris Basin, this effect is absorbed by the carbonate and sometimes improves the availability of phosphorus and trace elements. In soil that is already acidic, the pH must be monitored. This property explains why elemental sulfur is also used as a soil conditioner, a use distinct from sulfur fertilisation as such.

Elemental sulfur granules, powder, bentonite: which form to choose?

The form determines how fast agricultural elemental sulfur works. The finer the particle, the larger the surface exposed to bacteria. Sulfur bentonite, described in our article on bentonite sulfur, combines around 90% sulfur with a swelling clay that makes the granule burst on contact with water. According to Organic Grower, the released particles measure between 600 and 900 microns, with 10 to 15% clay.

Powder and micronised sulfur, covered in our article on micronised sulfur, oxidise even faster and are mainly used as a spray against powdery mildew: according to Techniloire, French vineyards use 10,000 to 12,000 tonnes of wettable sulfur and 4,000 to 6,000 tonnes of dusting sulfur every year.

Form of elemental sulfur Indicative content Oxidation speed Main use
Refinery granule or pastille 99,5 % (Organic Grower) Slow, several months to over a year Sulfuric acid, fertilizer raw material
Sulfur bentonite About 90% Intermediate, particles of 600 to 900 microns Base fertilizer, soil reserve
Powder and micronised Varies by product Fast Fungicide, quick correction

Agricultural elemental sulfur: price from the 25 kg bag to bulk

The price depends on scale. At retail, Hélinove lists a 25 kg bag of micro-granules at 36 euros excluding VAT, roughly 1,440 euros per tonne, a price that covers grinding, bagging and distribution.

At the other end of the chain, granulated sulfur is bought by the full shipload, and QatarEnergy's monthly contract reached 805 dollars per tonne FOB in June 2026 according to World Fertilizer, while CRU recorded a CFR Mediterranean price of 920 to 940 dollars in May, the highest since 2011. In between, the one-tonne big bag, delivered to an agricultural distributor or a packer, is negotiated on the basis of the bulk price plus bagging and transport. Our article on the price of sulfur per tonne explains how to read these quotations.

Elemental sulfur, a raw material before it is a fertilizer

Agricultural elemental sulfur accounts for only a small share of world production, most of which never reaches a field in its yellow form. One tonne of sulfur yields about three tonnes of sulfuric acid, according to World Fertilizer, and this acid is used to attack phosphate rock to produce DAP, TSP and single superphosphate, which itself contains sulfur in the form of calcium sulfate.

Of the roughly 39 million tonnes traded by sea each year, nearly 20 million passed through the Strait of Hormuz according to AGBI. The 2026 global sulfur crisis showed what happens to a fertilizer market when this raw material runs short: Argus Media reported delivered prices in Africa of 580 to 700 dollars per tonne as early as March 2026 for late March and early April loadings.

What E-Station does

E-Station supplies solid sulfur, as granules, pastilles or crushed lumps, to sulfuric acid producers, fertilizer manufacturers and distributors who pack it as agricultural elemental sulfur. Each lot comes with a certificate of analysis stating sulfur content, moisture and ash, with origins outside the Gulf, in bulk or big bags, and sea logistics organised through to unloading. Our sulfur trading hub presents the available grades, and our pages on sulfur in Morocco, sulfur in Algeria, sulfur in Senegal and sulfur in Côte d’Ivoire specify the ports and incoterms used in each market.

Frequently asked questions

Why does elemental sulfur act slowly as a fertilizer?

Agricultural elemental sulfur is insoluble in water and plants absorb only sulfate. Soil bacteria and fungi must first oxidise it, a process that depends on temperature, moisture, aeration and particle fineness, and that can take several months.

When should elemental sulfur be applied to a crop?

Elemental sulfur suits base applications, in autumn or on a previous crop, to rebuild the soil reserve. For a fast need, such as rapeseed stem elongation, Terres Inovia recommends the sulfate form. On cereals, Arvalis considers both forms equivalent if applied at tillering.

What is the difference between elemental sulfur granules and bentonite sulfur?

The refinery granule contains about 99.5% sulfur and oxidises slowly. Sulfur bentonite combines about 90% sulfur with a clay that makes the granule burst on contact with water into particles of 600 to 900 microns, which speeds up oxidation.

How much does elemental sulfur cost in 25 kg bags, big bags or bulk?

At retail, a 25 kg bag of micro-granules sells for around 36 euros excluding VAT from a French manufacturer. In bulk, the QatarEnergy contract reached 805 dollars per tonne FOB in June 2026 and CFR Mediterranean 920 to 940 dollars in May according to CRU. The big bag sits in between.

Does elemental sulfur acidify the soil?

Yes, its oxidation releases protons and lowers the pH locally. In calcareous soil, this effect is buffered and can improve phosphorus availability. In acidic soil, the pH should be monitored and liming planned accordingly.

You pack or process agricultural elemental sulfur and are looking for a certified non-Gulf origin delivered to your port. Request a quotation from E-Station to receive an offer in bulk or big bags.
Sulfur price per tonne: benchmarks, 2026 timeline and how to read them

Soufre jaune solide en granulés et concassé, négoce de soufre E-Station
Prix du soufre à la tonne : soufre jaune solide coté FOB Moyen-Orient et CFR Méditerranée, analyse de marché E-Station

Energy markets · Sulfur

Sulfur price per tonne: benchmarks, 2026 timeline and how to read them

From 173 dollars FOB Middle East in January 2025 to over 900 dollars CFR Mediterranean in spring 2026: the Argus, CRU and Kpler benchmarks for reading a sulfur quotation.

Request a quotation →

You look up the price of sulfur per tonne and find figures that vary by a factor of two from one page to the next. They are probably all correct. A sulfur price always comes with three details: the geographical benchmark, the incoterm and the date.

Solid sulfur is a by-product of oil refining and natural gas processing, sold as granules on ships carrying tens of thousands of tonnes. According to World Fertilizer, world demand exceeded 71 million tonnes in 2024, 60% of it for fertilizer production. The price of sulfur per tonne is quoted in dollars per metric tonne, with a few exceptions in long tons, and it reversed completely between 2025 and 2026. Our sulfur trading business relies on reading these quotations every day, and this article gives you the key to them.

Sulfur price per tonne in dollars: which benchmark to read?

A sulfur price per tonne can come from a dozen quotations published every week by Argus, CRU, ICIS or Platts. Each one describes a location, a product form and a delivery condition.

FOB Middle East and the QSP, KSP and ADNOC contract prices

The parent benchmark is the Argus Middle East Sulphur FOB, which covers bulk granular sulfur loaded in the main producing countries of the Gulf, excluding Iran, and serves as an index for many contracts between producers, traders and consumers. Alongside this market assessment, three state producers publish a monthly contract price: QatarEnergy with the QSP, Kuwait Petroleum Corporation with the KSP, and ADNOC in Abu Dhabi. In February 2026, according to World Fertilizer, the QSP stood at 520 dollars FOB Ras Laffan, the KSP at 520 dollars FOB Kuwait and ADNOC at 530 dollars FOB Ruwais for the Indian subcontinent.

Tampa, China, Brazil, Mediterranean: delivered sulfur price per tonne

The CFR price includes freight to the port of destination. In the United States, the quarterly Tampa contract covers liquid sulfur delivered to Florida phosphate plants and is set in long tons. In Asia, the benchmark is CFR China, the world’s largest importer with about 9 million tonnes a year according to AGBI. For a buyer in North Africa or West Africa, the useful quotation is CFR Mediterranean published by CRU, supplemented by CFR Brazil, which sets the tone for the South Atlantic.

Sulfur price per tonne: the 2025-2026 timeline

The movement started well before the geopolitical crisis. Argus Media notes that the FOB Middle East spot price rose from 173 dollars a tonne on 30 January 2025 to 531.50 dollars on 29 January 2026, driven by demand from Indonesian nickel refineries and by supply constraints in the former USSR and the Gulf. The closure of the Strait of Hormuz from the end of February 2026, described in our analysis of the 2026 global sulfur crisis, then turned a rise into a shortage.

Benchmark Sulfur price (USD/t) Date Source
Spot FOB Middle East 173 30 January 2025 Argus
Spot FOB Middle East 531,50 29 January 2026 Argus
QSP contract FOB Qatar 740 May 2026 CRU
CFR Mediterranean 920 to 940 May 2026 CRU
QSP contract FOB Qatar 805 June 2026 World Fertilizer
Tampa, liquid sulfur (USD/long ton) 705 Q3 2026 Fertilizer Daily

The May 2026 breakdown published by CRU shows the scale of the shock: the QSP at 740 dollars FOB was a record since the contract was created in August 2013, CFR Brazil reached 1,000 to 1,100 dollars, India traded between 800 and 850 dollars CFR, and the Mediterranean, at 920-940 dollars delivered, hit its highest level since the assessment began in 2011. In July, Fertilizer Daily reported a Tampa contract at 705 dollars per long ton for the third quarter, a US Gulf FOB spot price between 1,100 and 1,150 dollars and a Kuwaiti price raised to 950 dollars.

Why the price of sulfur per tonne remains so high today

Two mechanisms overlap. The first is physical and concerns the Strait of Hormuz; the second is regulatory and concerns China.

Hormuz and nearly half of traded sulfur

According to AGBI, of the roughly 39 million tonnes of sulfur traded worldwide each year, nearly 20 million pass through Hormuz. World Fertilizer puts the Gulf’s share at around 44% of traded sulfur. The analysis by Kpler puts the sulfur stuck on board ships in the Gulf at 600,000 tonnes at the April 2026 peak, with world exports down 45% from their end-February level. Morocco, Africa’s leading processor, received its last cargo from the Gulf on 10 April 2026, again according to Kpler.

China suspends its exports

China imports about 9 million tonnes a year, more than half of it from the Middle East, according to AGBI. On 10 April 2026, Beijing replaced its annual export quota of 700,000 tonnes with a complete halt until August 2026, according to Kpler. Buyers who were counting on Chinese sulfur had to look elsewhere, at a much higher cost.

Agricultural sulfur prices: from solid sulfur to the fertilizer bag

Agricultural sulfur sold to distributors, as powder, granules or incorporated into ammonium sulphate, follows the seaborne market price of sulfur per tonne with a lag of a few weeks. The chain is simple: one tonne of sulfur yields about three tonnes of sulfuric acid, according to World Fertilizer, and this acid attacks phosphate rock to produce the phosphoric acid used in DAP, TSP and MAP.

The World Bank Pink Sheet gives DAP at 781.30 dollars a tonne in July 2026 against an average of 685.20 dollars in 2025, and TSP at 719.50 dollars against 577.60 dollars. We explain this link in our article on sulfur and sulfuric acid, and the impact on Moroccan prices in the article on fertilizer prices in Morocco. Growers who use elemental sulfur directly as a fertilizer will find its forms and uses on our page on elemental sulfur in agriculture.

Sulfur price per tonne: how to read an offer when buying in North Africa or Africa

A serious offer states the quality, with the sulfur content, moisture and ash from the certificate of analysis, the form (granule, pastille or crushed lump), the packaging (bulk or big bags) and the incoterm. A sulfur price of 805 dollars per tonne FOB Middle East and a CFR Mediterranean quotation at 930 dollars describe the same market; the difference lies in freight, insurance and transit risk, all items we explain in our guide to incoterms and shipping documents.

The pages sulfur prices in Morocco and sulfur prices in Tunisia apply these benchmarks to the ports of Jorf Lasfar, Safi, Gabès and Sfax. For West Africa, the page sulfur delivery to Senegal details the constraints of the port of Dakar.

What E-Station does

E-Station tracks the price of sulfur per tonne every day, and buys and resells solid sulfur from origins outside the Gulf for sulfuric acid producers, phosphate fertilizer manufacturers and agricultural distributors. Each lot comes with a certificate of analysis, and shipping logistics are organised end to end, up to unloading, on FOB, CFR, CIF or DAP terms. The sulfur trading hub describes our grades and packaging. Canadian buyers have a dedicated page on sulfur in Canada, and our bitumen customers will find the same logistics organisation on the page bitumen trading.

Frequently asked questions

What is the price of sulfur per tonne in dollars in 2026?

According to CRU, QatarEnergy’s QSP reached 740 dollars FOB in May 2026 and CFR Mediterranean 920 to 940 dollars. World Fertilizer then reports a QSP of 805 dollars for June 2026. The price of sulfur per tonne therefore depends on the benchmark, the incoterm and the date.

Why has the price of sulfur risen so much?

Demand from nickel refineries in Indonesia had already tripled the FOB Middle East price between January 2025 and January 2026, according to Argus. The closure of the Strait of Hormuz at the end of February 2026, followed by the halt to Chinese exports in April, then removed a large part of seaborne supply from the market.

What is the difference between a FOB and a CFR sulfur price?

The FOB price applies to goods loaded on board at the port of departure, without freight or insurance. The CFR price includes sea transport to the port of destination. The gap between the two is the freight, which has risen sharply since 2026 on routes avoiding the Gulf.

How does the price of sulfur affect fertilizer prices?

One tonne of sulfur produces about three tonnes of sulfuric acid, needed to turn phosphate rock into DAP, MAP or TSP. The World Bank reports DAP at 781 dollars a tonne in July 2026 against an average of 685 dollars in 2025.

Where can you find today’s sulfur price?

Benchmark quotations are published by Argus, CRU, ICIS and Platts on subscription, and monthly contract prices by QatarEnergy, KPC and ADNOC. A trader like E-Station turns these benchmarks into a firm offer for a given port, quality and volume.

You need a firm sulfur price per tonne, delivered to your port, with a certificate of analysis and an origin outside the Gulf. Request a quotation from E-Station, stating the volume, form and incoterm you want.

Sulfur for oilseed rape: needs, rate and timing, unit by unit

Soufre en poudre jaune, matière première des engrais soufrés négociée par E-Station
Soufre colza : granulés de soufre jaune pour la fertilisation soufrée du colza, matière première négociée par E-Station

Agronomy · Sulfur

Sulfur for rapeseed: requirements, rate and timing, unit by unit

Rapeseed absorbs nearly 200 kg of SO3 per hectare and loses up to 20 q/ha when sulfur is lacking. Here are the rate, stage and form recommended by Terres Inovia, with sources.

Request a quotation →

You sowed your rapeseed at the end of August, the nitrogen is planned, and one question remains that many deal with last: how much sulfur, in what form and when? Sulfur for rapeseed is calculated to the unit, exactly like nitrogen, and decided with a growth stage in mind.

Rapeseed is the most sulfur-hungry major field crop in the European cereal system. According to the Journal Paysan Breton, which draws on Terres Inovia references, its total requirements are around 200 kg of SO3 per hectare, and a deficiency costs up to 10 or even 20 quintals. Since atmospheric fallout dropped, sulfur for rapeseed has come from fertilizer, and therefore from an industrial chain that starts with the solid sulfur described on our page on sulfur trading. This article gives you the agronomic benchmarks, then explains where the raw material of the fertilizer your cooperative sells you comes from.

What is the sulfur requirement of rapeseed, unit by unit?

Rapeseed is a brassica, and brassicas produce glucosinolates and proteins rich in sulfur amino acids. The French Academy of Agriculture places rapeseed in the group of crops whose requirements exceed 100 kg of SO3 per hectare, far ahead of straw cereals, which are between 50 and 100 kg.

The same source notes that atmospheric sulfur deposition has fallen sevenfold in thirty years and now supplies only about 11 kg of SO3 per hectare. The soil does not make up the difference: more than 80% of soil sulfur is stored in organic form, and the sulfate ion, the only form directly available, is very mobile and leaves with the winter rains.

The timing of uptake matters as much as the quantity. Again according to Paysan Breton, uptake becomes strong very early at the end of winter, from the start of stem elongation at stage C2. At that point, the plant builds its biomass in a few weeks and has no time to wait for an organic stock to mineralise. That is why sulfur for rapeseed is planned in units applied, with a date, rather than as a soil reserve alone.

Sulfur and nitrogen work together in rapeseed

On a sulfur-deficient crop, the nitrogen applied accumulates in non-protein form and yield plateaus. AgroLeague cites a total S to total N ratio of around 5 to 1 in brassicas, against 10 to 1 in cereals. The same article states that an application limited to 25 units per hectare results in a drop of around 10 q/ha compared with the 75-unit sulfate threshold.

How many units of sulfur on rapeseed?

For sulfur on rapeseed, Terres Inovia's recommendation has been stable for years: 75 kg of SO3 per hectare, in sulfate form, applied systematically. The Terres Inovia Hauts-de-France sheet uses this 75-unit rate, in available sulfate form, from the start of stem elongation. This rate applies to the vast majority of plots, including on deep soils.

When can the rate go down to 50 units?

Only one situation allows a downward adjustment. On plots that regularly receive organic matter, manure or slurry, Paysan Breton indicates an application of around 50 units of SO3 instead of 75. Terres Inovia sets this floor at 50 units and advises against going lower, even with regular organic inputs. The AgroLeague survey specifies that manures contain between 1 and 3 kg of sulfur per tonne and that poultry manure is the richest, which explains why only regular applications count in the calculation.

Plot situation Sulfur rate for rapeseed (SO3/ha) Benchmark
General case, no regular organic inputs 75 kg, sulfate form Terres Inovia
Regular manure or slurry applications 50 kg, a floor not to be crossed Paysan Breton / Terres Inovia
Correction of visible deficiency 60 kg as ammonium sulfate diluted in 500 l of water Fertilisation-edu (CETIOM)

When should sulfur be applied to rapeseed in the field?

The window is short and well defined. Paysan Breton places the application together with the first or second nitrogen application, between stages C2 and D1, that is, between the appearance of internodes and closed buds. North of the Loire, the source advises waiting until the end of February. Applying earlier exposes the sulfate to January leaching, while applying later misses the uptake peak of stem elongation.

The 350 mm rainfall threshold

Sulfate follows water. Terres Inovia considers that above 350 mm of cumulative rainfall from November to February, the risk of sulfur leaching is high. In Hauts-de-France, the 2024-2025 season saw several stations exceed this threshold, with shallow, free-draining soils particularly exposed. In these conditions, the autumn sulfate stock has gone into the drains, and the spring application becomes the only source available for stem elongation.

In what form should sulfur be applied to rapeseed?

Rapeseed will not wait. The sulfate form is directly available, whereas elemental sulfur and thiosulfate must first be oxidised by soil micro-organisms, as noted on the website Fertilisation-edu. Paysan Breton confirms that sulfate forms should be preferred, combined with another nutrient: ammonium sulfate, sulfur-enriched ammonium nitrate or sulfur-enriched nitrogen solution. We detail these products in our article on nitrogen-sulfur fertilizer and, for liquid forms and ammonium thiosulfate, in our article on liquid sulfur fertilizer.

Elemental sulfur fits into a different logic: applied in autumn or on a previous crop, it releases sulfate gradually and feeds the soil stock. On rapeseed, it is a useful complement to a spring sulfate application, which remains essential at stem elongation.

Recognising deficiency and correcting it

A deficiency can be spotted in spring by young leaves mottled with yellow, pale flowers and poorly filled pods. We devote a full article to it on sulfur deficiency in rapeseed. Correction is possible: Fertilisation-edu cites the CETIOM recommendation of 60 kg of SO3 per hectare as ammonium sulfate diluted in 500 litres of water. Correction saves part of the yield, never all of it, which argues for preventive application.

The origin of the sulfur in your fertilizer

Ammonium sulfate, sulfur-enriched ammonium nitrate and single superphosphate contain sulfur from a single raw material: solid sulfur, a co-product of refining and gas processing. According to World Fertilizer, world sulfur demand exceeded 71 million tonnes in 2024, 60% of it for fertilizer production.

The 2026 global sulfur crisis, triggered by the closure of the Strait of Hormuz, pushed the Middle East FOB price from 173 dollars per tonne at the end of January 2025 to 531.50 dollars at the end of January 2026, according to Argus Media, before new records in spring. The price of the 75 units of sulfur for rapeseed therefore depends on the availability of solid sulfur at the fertilizer manufacturer, in France as in Belgium.

What E-Station does

E-Station supplies solid sulfur to fertilizer manufacturers, sulfuric acid producers and distributors who formulate the rapeseed sulfur fertilizers sold in growing areas. The sulfur is offered as granules, pastilles or crushed lumps, in bulk or big bags, with a certificate of analysis per lot and origins outside the Gulf, which has mattered since the tensions over Hormuz.

Our sulfur trading hub presents the available grades, and our pages on sulfur in France and sulfur delivery in France describe the sea logistics through to unloading, on FOB, CFR, CIF or DAP terms. Belgian and Swiss manufacturers will find the same information on sulfur in Belgium and sulfur in Switzerland.

Frequently asked questions

How much sulfur should be applied to rapeseed?

For sulfur on rapeseed, Terres Inovia recommends 75 kg of SO3 per hectare in sulfate form, systematically. On plots that regularly receive manure or slurry, the rate can be reduced to 50 units, but never below.

When should sulfur be applied to rapeseed?

The application is made with the first or second nitrogen application, between stages C2 and D1, at the start of stem elongation. North of the Loire, Terres Inovia advises waiting until the end of February to limit leaching.

Why does rapeseed need so much sulfur?

Rapeseed is a brassica that synthesises glucosinolates and proteins rich in sulfur amino acids. Its total requirements reach about 200 kg of SO3 per hectare, and a deficiency can cost 10 to 20 q/ha according to Terres Inovia.

Which form of sulfur should be chosen for rapeseed?

The sulfate form is directly available and suits the uptake peak during stem elongation. Ammonium sulfate, sulfur-enriched ammonium nitrate and sulfur-enriched nitrogen solution are the most common carriers, while elemental sulfur acts more slowly.

How much does sulfur deficiency cost on rapeseed?

Terres Inovia puts the yield loss at between 10 and 20 q/ha in situations of marked deficiency. A foliar or soil correction with ammonium sulfate limits the damage, without restoring the initial potential.

You manufacture or distribute the fertilizers that supply sulfur for rapeseed and are looking for certified solid sulfur supply from outside the Gulf, delivered to the port of your choice. Request a quotation stating the annual tonnage and discharge port, and you will receive a dated proposal backed by a certificate of analysis.

Global sulfur crisis: why phosphate fertilizer prices are soaring in 2026

Soufre jaune solide en granulés et concassé, négoce de soufre E-Station
Soufre en poudre : la crise mondiale du soufre de 2026 renchérit les engrais phosphatés
Energy markets · Sulfur

Global sulfur crisis: why phosphate fertilizer prices are soaring

Hormuz blockade, export quotas, fertilizer plants shut down: what the sulfur crisis changes for farmers and manufacturers, from Morocco to Canada.

Request a quotation →

Since the end of February 2026, the closure of the Strait of Hormuz has deprived the world market of half its seaborne sulfur. Phosphate fertilizer manufacturers, smelters and mines are absorbing the shock one after another, and farmers are set to pay for it in the autumn.

Nitrogen usually dominates conversations about fertilizer prices. This year, the subject is phosphate, and behind phosphate lies a raw material few farmers have ever seen: sulfur. It is burned to make sulfuric acid, which then attacks phosphate rock to produce phosphoric acid, and then the DAP and MAP spread in the fields. When sulfur runs short, the whole chain seizes up. Our page on sulfur trading describes this product and the forms in which it is bought.

Hormuz and the world sulfur trade

Sulfur is a by-product of oil refining and gas processing. The major Gulf producers, Saudi Arabia, the Emirates, Qatar and Kuwait, ship it from their ports, and these ships pass through the Strait of Hormuz. According to the Institute for Security Studies (ISS), about half of the sulfur used in phosphate fertilizers passes through this strait. Since the outbreak of the conflict in the Middle East at the end of February 2026, these cargoes have been delayed, diverted or blocked, to the point that Iraq is selling its crude at a discount to keep exporting.

The three causes of the rise

The blockade could have been absorbed by other origins if three major producers had not closed their borders at the same time. China, Russia and Turkey restricted their exports of sulfur and sulfuric acid in the first half of 2026 to protect their own fertilizer plants. China suspended its sulfuric acid sales in April, which immediately hit copper mines in the Democratic Republic of the Congo. Buyers then competed for the remaining cargoes, loaded in the Mediterranean, the Black Sea or Canada. The result is a rise in the sulfur price unmatched in recent memory and volatility that makes any quotation perishable within a few days.

The sulfuric acid shortage

Sulfuric acid is the most widely produced chemical in the world, and fertilizers take the largest share. Fortune Business Insights notes that phosphoric acid production, and therefore phosphate fertilizers, is its main outlet, ahead of chemicals, metal treatment and refining. When sulfur accounts for most of the production cost of this acid, a DAP manufacturer sees its margin disappear within weeks. Shutdowns or production cuts were reported in Brazil and Egypt during summer 2026, further reducing the fertilizer supply available for autumn sowing.

The consequences for the mining industry

Copper, nickel and cobalt are extracted by acid leaching. In the first quarter of 2026, the DRC saw its sulfuric acid imports collapse after Zambian and Chinese export restrictions, and its miners switched to buying sulfur to produce acid on site. Our page on buying sulfur in the DRC details this market and its logistics corridors from Dar es Salaam, Durban or Walvis Bay.

The most exposed African countries

The ISS lists Ethiopia, Côte d’Ivoire, Zambia, Kenya and the DRC among the most exposed net fertilizer importers, and points out that South Africa imports 80% of its agricultural inputs. The continent is also a producer: Morocco processes its phosphate at Jorf Lasfar and Safi, Tunisia at Gabès, Sfax and Skhira, and Senegal at Darou Khoudoss. These three industries burn imported sulfur, much of which came from the Gulf. They are now looking for fallback origins, as explained on our pages on sulfur in Morocco, the sulfur in Tunisia and sulfur in Senegal. In Côte d’Ivoire, the Abidjan blenders supplying cocoa and cotton growers also depend on these flows; see buying sulfur in Côte d’Ivoire.

Europe and Canada: opposite situations

France remains a net importer of sulfur despite the output of its refineries, and its sulfuric acid manufacturers, port fertilizer plants and winegrowers use it all year round. Through FranceAgriMer, the Ministry of Agriculture opened an aid scheme for purchases of mineral nitrogen fertilizers made between 1 June and 30 September 2026, with applications possible until 6 November 2026. Phosphates are not covered by this scheme. Details of ports and buyers are on our page on buying sulfur in France.

Canada is in the opposite situation: Alberta exports millions of tonnes of sulfur a year and is breaking records in 2026, but this sulfur goes to Asia via Vancouver, far from buyers in Quebec. Our page on sulfur in Canada describes this paradox.

What farmers can do

Sulfur is also a nutrient. Soybeans, for example, need more of it to synthesise their oil, and soil micro-organisms release it more slowly when the soil is cold, as Tessenderlo Kerley points out. A farmer who cuts phosphate applications this year should therefore also keep an eye on sulfur applications. Unlike nitrogen, phosphate is stored in the soil, which allows a year of restraint if recent analyses permit it. Agronomists recommend moving away from systematic spreading and planning field by field, on the basis of soil analysis, so as to apply only what the crop will actually remove.

What E-Station does

As an energy broker, E-Station supplies manufacturers with solid sulfur loaded away from exposed sea routes, with a certificate of analysis and a single contact through to unloading. The price is made up of the reference price, the origin, the product form and freight: our page on sulfur prices in Morocco explains how to read a quotation. Logistics, from bulk carrier to container of big bags, are described country by country, for example for sulfur delivery to Senegal or sulfur delivery in France. The same principles apply to our long-standing business of bitumen trading, and Incoterms and export documents are common to both products.

Frequently asked questions

Why does sulfur weigh so heavily on the price of phosphate fertilizers?

Because sulfuric acid is needed to turn phosphate rock into phosphoric acid, and then into DAP or MAP. Sulfur is the main raw material for this acid: when it runs short or becomes more expensive, the cost of fertilizer follows.

Which countries are hit hardest by the sulfur crisis?

Net fertilizer importers in sub-Saharan Africa, North African fertilizer producers that burned Gulf sulfur, and copper and cobalt mines in the DRC deprived of acid. Sulfur-exporting countries such as Canada benefit.

Can a farmer postpone phosphate applications?

Phosphate is stored in the soil, which allows a year of reduced application if a recent soil analysis confirms it. Postponing becomes risky if the crisis drags on and soil reserves are low.

Where does E-Station load its sulfur?

From refineries and gas processing units whose ports remain accessible whatever the situation in the Gulf, notably in the Mediterranean and the Black Sea. The sulfur trading page details the guaranteed specifications.

Sources: ISS Africa, "The Strait of Hormuz threatens Africa's food supply" ; Fortune Business Insights, sulfuric acid market ; Kpler, the 2026 sulfur and sulfuric acid crisis ; Sika Finance, acid shortage in the DRC ; Le Paysan Tarnais, aid for nitrogen fertilizer purchases ; Tessenderlo Kerley, sulfur and potassium for soybeans.

Need sulfur for your plant? E-Station issues a dated quotation, form by form, with a certificate of analysis and specified delivery conditions. Request a quotation.

Oil: squeezed by the Hormuz blockade, Iraq sells its crude at a discount to save its finances

Soufre élémentaire jaune destiné aux fabricants d'engrais et d'acide sulfurique, E-Station
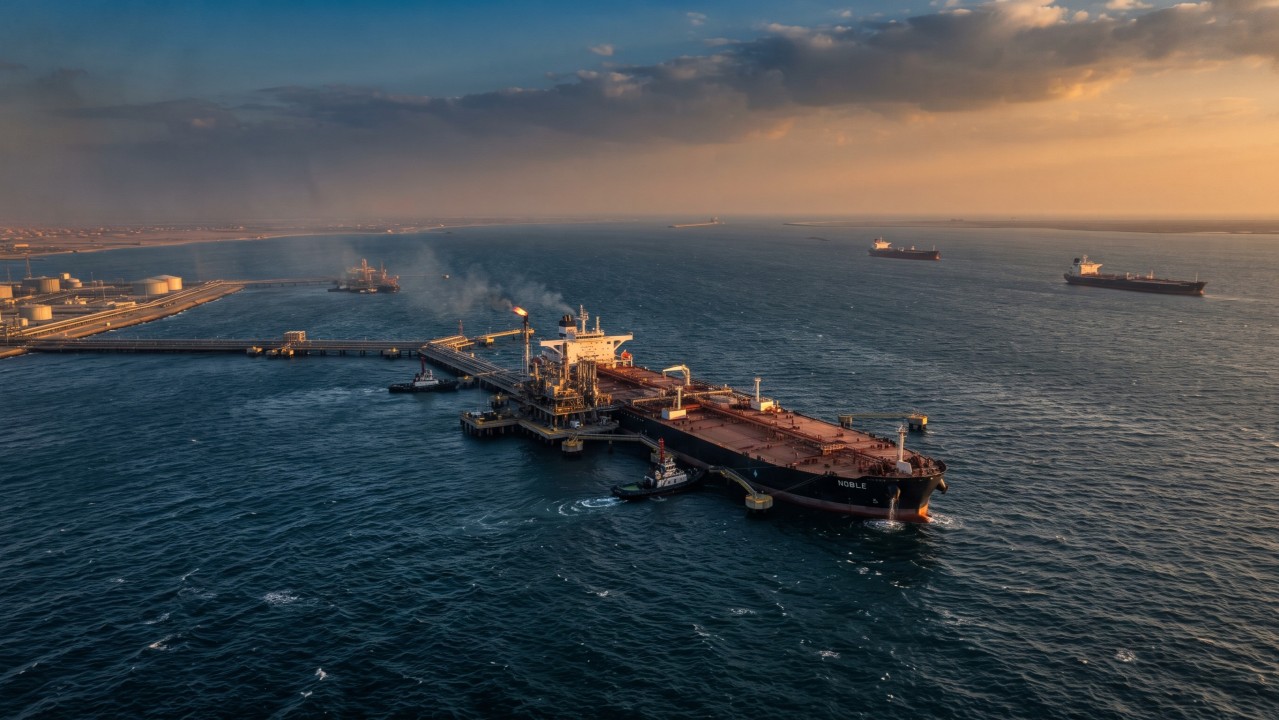
Terminal pétrolier et pétroliers au large : l'Irak réorganise ses exportations de brut face au blocage du détroit d'Ormuz
Energy markets · Crude oil

Oil: squeezed by the Hormuz blockade, Iraq sells its crude at a discount to save its finances

Discounts on Basrah grades, transshipments off Fujairah, oil revenues halved: how Baghdad is trying to keep its exports going.

Request a quotation →

Faced with the collapse of shipping flows in the Strait of Hormuz, Baghdad is granting massive discounts on its crude and reorganising its export logistics to avoid budgetary suffocation. For buyers, the window is real, provided the logistics risk is under control.

Record discounts to keep customers

Iraq sells its oil through SOMO, the state marketing organisation. Since the August 2026 cargoes, SOMO has made official discounts of an unprecedented size on Basrah Medium and Basrah Heavy, to offset the surge in freight and insurance premiums for ships still crossing the strait. A supertanker chartered on these routes now costs several times its pre-crisis rate, and this extra cost comes straight off the price the buyer agrees to pay.

A new export mechanism since 1 September

The Iraqi Council of Ministers approved a flat-rate discount mechanism applicable since 1 September, and opened logistics to specialised private operators. Crude can thus be loaded onto shuttle vessels and then transshipped at sea, ship to ship, off Fujairah, on the east coast of the Emirates, outside the strait. Asian refiners and charterers organise these chains to secure their volumes without exposing their own tankers to the regional risk.

A budget that rests on oil

This logistical paralysis threatens the country’s macroeconomic stability. Ministry of Finance figures for the first half of 2026 show oil revenues halved compared with the same period of 2025, and a widening deficit. Operating expenditure, salaries, pensions and subsidies, absorbs 85% of the budget, which leaves the State with no room for manoeuvre until exports have recovered half their pre-crisis pace.

Consequences for a crude buyer

Two routes are open. The first is to buy discounted Iraqi crude, accepting a supply chain that runs through Fujairah, with its transshipments, insurance and lead times. The second is to turn to non-Gulf origins, whose ports remain accessible. In both cases, the discipline is the same: a clearly defined incoterm, insurance suited to the zone and a complete set of documents. These rules are described on our page on incoterms and shipping documents, valid for all petroleum products, and on the one devoted to the letter of credit.

Derived products follow the same movement

Iraqi crude also feeds the region’s refineries, whose sales come from jet fuel, from bitumen and sulfur. The Hormuz blockade has therefore spilled over into these markets: the global sulfur crisis that is driving up the price of phosphate fertilizers is its most visible consequence.

What E-Station does

We work in crude oil trading and its derivatives, with a single point of contact from quotation to delivery. For buyers in North and West Africa, we offer origins whose route avoids the Gulf, and we frame the incoterm and insurance from the offer stage, as we do for sulfur in Morocco or bitumen delivery in Africa.

Frequently asked questions

Why is Iraq granting discounts on its crude?

To offset the extra freight and insurance costs borne by buyers whose ships cross the Strait of Hormuz, and to keep its market share in Asia during the crisis.

What is a ship-to-ship transshipment off Fujairah?

The crude is loaded onto a shuttle vessel in the Gulf, then transferred at sea to an ocean-going tanker off Fujairah, on the Gulf of Oman side, which spares the large vessel from crossing the strait.

What is the risk for a buyer of discounted Iraqi crude?

Lead time, insurance and documentation. A discount only has value if the crude arrives: the incoterm, the cover for the zone and the document checks must be settled before any commitment.

Do you offer non-Gulf origins?

Yes, for crude and for its derivatives, with loading ports that remain accessible whatever the situation in the strait.

Need crude oil or refined products? We draw up a priced offer with origin, incoterm and payment terms specified. Request a quotation.

Bitumen market in Africa 2026: how to secure your supply amid fragile stabilization

Chantier de construction routière avec rouleau compresseur, illustration de la pénurie de bitume
Marché du bitume en Afrique : chantier de construction routière illustrant la sécurisation des approvisionnements en 2026

The African bitumen market has changed in nature. For procurement directors, construction companies and infrastructure ministries across the continent, the first half of 2026 brought a harsh lesson: the cost of a road project now depends as much on the strength of its supply chain as on the price of crude.

The recent market analysis published by Infinity Galaxy highlights a major transition. Between February and April 2026, the African bitumen market went from a precarious balance to a real price shock caused by global geopolitical tensions and shipping blockages. While mid-year marks the start of a stabilisation phase, it remains particularly fragile. For economic operators, the situation has changed: a return to pre-crisis conditions is not on the agenda. This tension shows directly in bitumen prices.

Logistical differences between East and West Africa

The African bitumen market no longer reacts as a single block to global fluctuations. Regional dynamics have become deeply fragmented:

  • In East Africa (Kenya, Tanzania): buyers bear the full brunt of the direct disruptions to maritime flows from the Middle East and the Strait of Hormuz. Freight costs and insurance premiums on discharge at Mombasa or Dar es Salaam keep spot prices at very high levels.
  • In West and Central Africa (Congo-Brazzaville, DRC, Angola): the situation is different. These markets traditionally relied on European refining surpluses (notably from the Mediterranean). Technical shutdowns and force majeure declarations by several European refineries have dried up the usual flows.

In a fast-growing area such as the Congo Basin, the success of a transport or road access project now depends less on driving the price down than on absolute availability guarantee of the cargoes. We detail these issues on our page on bitumen delivery in Africa.

Buying bitumen in Congo and the DRC: the question of packaging

To secure a bitumen purchase in Congo or the Democratic Republic of the Congo (DRC), technical flexibility has become the main weapon of experienced buyers. Large imports by heated bitumen tankers face heavy port constraints and prohibitive demurrage costs in Central African ports.

That is why alternative delivery solutions are gaining ground in 2026:

  • Bitumen in jumbo bags (1,000 kg): ideal for multi-modal transport to inland destinations (the Pointe-Noire/Brazzaville route, or from the port of Matadi to Kinshasa). It eliminates the risk of the product cooling and simplifies on-site storage.
  • Bitumen in drums (new steel drums): a safe bet for long-term storage and for protecting the bituminous binder against tropical weather and intense rainy seasons.
  • Suitable penetration grades: whether bitumen 60/70 or bitumen 80/100, consistent quality and certified viscosity in line with the bitumen (asphalt) are essential to ensure the durability of asphalt mixes under heavy loads and the region's high temperatures.

The choosing the right packaging (drums, big bags, bulk) is therefore decisive for the success of your worksites in Central Africa.

Bitumen market in Africa: anticipating volatility in the second half of 2026

Waiting for a hypothetical drop in oil prices is a risky strategy. The scarcity of heavy refining residues and the cost of global maritime transport keep landed costs under pressure on the sub-Saharan African bitumen market. The key to performance lies in diversifying sourcing origins (Southern Europe, Turkey, the UAE) and building in flexible logistics clauses from the moment contracts are signed.

At E-Station, we understand the operational realities of infrastructure in Africa. Through our international distribution network and our command of maritime and overland freight, we secure your bitumen volumes, in drums or jumbo bags, right up to your production sites. This is the essence of our bitumen trading and supply.

Immediate needs or planning your next road supplies? Our teams analyse your flows to offer you the best contractual flexibility.

Secure your purchase

Optimise your imports and secure your bitumen purchase in Africa, in drums or jumbo bags.

Secure my bitumen purchase

Frequently asked questions about the bitumen market in Africa

Why did the bitumen market in Africa experience a price shock in 2026?

Between February and April 2026, global geopolitical tensions and maritime blockages tipped the African bitumen market from a precarious balance into a genuine price shock, putting pressure on the continent's supply chains.

Does the stabilization observed in mid-2026 mean a return to normal?

No, this stabilization remains fragile. A return to pre-crisis conditions is not on the horizon, and operators must contend with a market that is structurally tighter than before.

What now determines the cost of a road construction project in Africa?

Cost no longer depends solely on the price of crude oil, but also on the strength of the logistics chain: vessel availability, maritime freight, and supply reliability.

Who is affected by this shift in the African bitumen market?

Procurement directors, construction companies, and the continent's infrastructure ministries, who must secure their supplies in the face of this persistent volatility.

How can bitumen supplies be secured in this context?

A specialized broker helps anticipate logistics tensions, diversify supply sources, and secure volumes on controlled terms despite market volatility.

The bitumen market paradox in 2026: when fleet capacity growth meets volatile supply lines

Paradoxe du marché du bitume 2026 : flottes et approvisionnement
Marché du bitume 2026 : fûts en attente de chargement et flotte de navires-citernes

The global bitumen market enters the second half of 2026 in a state of complex imbalance. For infrastructure developers, procurement managers and logistics operators, the current landscape defies the usual logic of commodities: on one side, a wave of fleet renewal is launching larger and more efficient ships; on the other, chronic geopolitical disruption at key maritime chokepoints, first and foremost the Strait of Hormuz, continues to choke the supply of heavy crude, keeping refinery output restrained.

According to the mid-year analysis published by BRS Shipbrokers, the market is defined by a clear paradox: supply fundamentals are technically improving, but structural feedstock problems prevent output from jumping as it would have in the past. At the same time, infrastructure demand remains highly fragmented worldwide. For companies operating in this environment, understanding the bitumen market and the meeting point between refinery caution, regional weather hazards and tanker fleet expansion is essential to protect project margins. This context weighs directly on the price of bitumen.

Why refineries are limiting bitumen production

The root of the current supply tension does not lie in bitumen production units themselves, but much further upstream. The persistent disruptions to crude flows through the Strait of Hormuz have profoundly altered refiners’ behaviour in 2026.

Bitumen production relies largely on vacuum residue from the refining of heavy, sour crudes. Because these specific grades face periodic and severe bottlenecks on leaving the Gulf, refiners operate with extreme caution. Rather than increasing throughput to meet seasonal construction demand, they prefer to keep stocks tight.

This upstream bottleneck explains why global bitumen production has not seen its usual summer peak. Supply disruptions sustained high price levels throughout the first half of 2026, creating an environment where fears of shortage are driven by geopolitical friction rather than any genuine lack of refining capacity. As long as maritime routes out of the Middle East carry a high risk premium, refiners will hardly increase product allocation to low-margin heavy residues like bitumen in the short term.

Demand that differs by region

While supply remains tightly constrained by geopolitical realities, global demand for bitumen in the second half of 2026 presents a deeply contrasted picture. The market’s traditional growth engine, the Asia-Pacific region, is experiencing a marked slowdown. The combination of severe monsoons, weather anomalies and bureaucratic delays in public infrastructure spending has heavily curbed road-paving works. South-East Asian governments have slowed project execution, leading to a temporary dip in direct import demand. While analysts expect a seasonal recovery in the fourth quarter as the weather improves, a lasting rebound will require a major injection of public capital and the swift unblocking of stalled road programmes.

By contrast, Europe and its trading basins form a highly localised picture:

  • Northern Europe: countries such as Sweden, Norway, Denmark and Finland stand out. Driven by expanded public budgets specifically dedicated to long-term road maintenance and climate-resilient rehabilitation, paving activity is showing solid signs of recovery.
  • The Mediterranean balancing basin: the production surplus of Southern European refiners is increasingly being absorbed by North African markets.
  • North Africa: Algeria, Morocco and Libya are generating the strongest incremental demand in the western hemisphere. Driven by vast national infrastructure corridors and ambitious road programmes, these nations are acting as a vital outlet for Mediterranean barrels.

This trend confirms the region’s rise: see our dedicated analysis of the bitumen delivery in Africa and our outlets in the Maghreb.

Transport: more ships for weak demand

In the bitumen market, the most significant structural shift highlighted by BRS Shipbrokers is playing out on the water. The global fleet of specialized bitumen tankers is in the midst of a major, historic renewal cycle.

Today, the world fleet counts 267 specialised ships, with an average age of 14.5 years and an average capacity of around 8,900 deadweight tonnes (dwt). But a sustained and aggressive newbuilding programme is quickly introducing a new generation of ships. Most of these deliveries are in the 8,500 to 17,500 dwt segment, alongside a few exceptionally large units.

This shift marks a clear break from the traditional 3,000 to 10,000 dwt ships that historically dominated coastal trade in the Mediterranean and North-West Europe. The new generation offers significant economies of scale, designed to aggressively reduce the transport cost per tonne of liquid bitumen.

However, the timing of these deliveries has created a serious commercial mismatch. These highly efficient, high-capacity vessels are arriving on the market at the very moment when actual cargo volumes remain constrained by refinery caution and slowing public spending. Moreover, the scrapping of older, less efficient vessels has not been fast enough to offset this influx of new capacity.

Consequently, unless public infrastructure spending accelerates markedly in the coming months, the growth in fleet capacity will trigger intense competition between shipowners for available cargoes. For procurement teams, this transport overcapacity offers a rare bright spot: it puts persistent downward pressure on spot freight rates on Mediterranean, North-West European and African routes, partly offsetting the high premium on the commodity itself.

Consequences for buyers

The reality of the late-2026 market means that resilience can no longer rest on traditional purchasing models. When shipping capacity is high but feedstock availability remains volatile, operators must build absolute flexibility into their sourcing strategies.

Relying solely on specialised tankers to deliver liquid product to coastal terminals exposes projects to the direct fallout of refinery force majeures and chokepoint blockages. To mitigate this risk, the most forward-thinking infrastructure firms are increasingly turning to containerised, solid-state logistics. Using jumbo bags and specialised drums makes it possible to decouple their supply chains from the tight market for specialised tankers. By using standard container ships or multimodal land networks, buyers can source bitumen from stable balancing basins, such as the Turkish or Greek markets, and deliver it directly to inland projects without the risk of demurrage or delivery interruptions.

Contractual structures must adapt too. Contracts drafted in the current climate need flexible origin clauses and robust freight-rate mechanisms, allowing buyers to capitalise on the downward pressure in the shipping market while hedging against sudden feedstock spikes. Our documentary logistics and Incoterms expertise secure each of these steps.

Bitumen market: the second half of 2026

The balance of risks for the rest of the year points to a gradual stabilisation of supply, combined with a modest and highly seasonal rebound in demand in the fourth quarter. A genuine, lasting market recovery, however, remains entirely dependent on structural shifts: the stabilisation of crude corridors out of the Gulf and a renewed commitment by major importing countries to infrastructure spending.

Until these macroeconomic factors align, the specialised bitumen sector will remain highly competitive and sensitive to local dynamics. Success in this environment belongs to those who look beyond the refinery gate, monitor the structural shifts of the global fleet and leverage diversified logistics channels to secure their margins. This is precisely the approach we bring to our bitumen trading and supply.

At E-Station, we bridge the gap between volatile refinery output and your project timelines. By closely analysing global maritime data and deploying flexible, multi-origin sourcing solutions, we ensure your infrastructure supply chain stays uninterrupted, whatever the shifts on the global map.

Optimise your sourcing

Let’s optimise your sourcing strategy for the season ahead, between volatile supply and freight under pressure.

Secure my supply chain

Frequently asked questions about the bitumen market

What is the paradox of the bitumen market in 2026?

Supply fundamentals are technically improving thanks to fleet modernization, but structural feedstock issues and tensions in the Strait of Hormuz continue to choke production, creating an unprecedented imbalance.

Why isn't fleet modernization enough to stabilize the market?

New, larger and more efficient vessels are being launched, but this additional capacity does not offset the chronic disruptions at key maritime chokepoints that limit heavy crude supply.

What role does the Strait of Hormuz play in this imbalance?

Geopolitical disruptions at this strategic chokepoint continue to slow heavy crude supply, keeping refinery production under strain despite sustained demand.

Who is most exposed to this bitumen market volatility?

Infrastructure developers, procurement managers, and logistics operators, whose project planning depends directly on supply stability.

How can buyers adapt to this volatile environment?

By relying on a broker who monitors these dynamics daily, it becomes possible to anticipate supply tensions and secure volumes before volatility affects prices.

When Hormuz tightens, your road budget takes a hit: why freight is the real price of bitumen

Pipeline de pétrole brut reliant l'Irak à la Turquie
Prix du bitume : pipelines et chaîne de fret maritime qui déterminent le coût rendu

The price of bitumen is no longer decided at the refinery. Maritime chokepoints are often associated with gas pumps or financial market jitters. But for those running infrastructure projects, the reality is far more concrete: it shows up in the cost of the black, sticky binder that holds our roads together.

While petroleum bitumen (HS 271320) represents only a fraction of a crude-oil barrel, it depends entirely on the same global logistics chain. It shares the same specialised heated tankers, is subject to the same war-risk premiums, and waits in the very same maritime queues.

The tightening of the Strait of Hormuz in early 2026 was a sharp reminder of this vulnerability. As Middle East tanker freight rates soared to highs not seen in two decades, the cost of laying asphalt jumped within weeks. It became clear that, in today’s market, the real price of the product — price of bitumen is driven by freight rather than by refinery output.

The weight of logistics in the price of bitumen

The price of bitumen is not a figure like any other, because it is not a commodity like any other. Because it must be kept hot in highly specialized vessels, or carefully packed into jumbo bags and drums, its supply chain is inherently regional and extremely sensitive to transport shocks.

Four major corridors structure global trade:

  • North America: Canada supplying the United States directly.
  • Middle East: the Gulf supplying India and East and Southern Africa.
  • Asia-Pacific: Singapore acting as a vast blending and redistribution hub for South-East Asia and Australia.
  • Mediterranean: a flexible swing basin linking Southern Europe (Greece, Turkey, Spain, Italy) to North and West Africa.

When a single chokepoint like Hormuz seizes up, the shockwave ripples through all these corridors. India, which imports nearly 2.8 million tonnes of bitumen a year from Iraq and the Emirates to sustain its frantic road-building cycle, feels the effects first. At the same time, a force majeure at Singapore’s major refineries can instantly reverberate as far as Australia and Indonesia, forcing them to source barrels thousands of kilometres away.

Bitumen price: the costs after the refinery

For procurement managers, engineers and infrastructure financiers, treating bitumen as a simple, predictable budget line is no longer tenable. Project resilience now rests on securing the most reliable supply corridor, not merely on finding the cheapest supplier.

To protect their margins from sudden maritime inflation, savvy operators are adapting their strategies:

  • Diversify origins: no longer depending entirely on a single geographic source.
  • Rethink packaging: incorporating flexible containerised solutions, such as jumbo bags or drums, to secure overland or alternative routes without relying solely on the rare and costly bitumen tankers.
  • Build in buffers: drafting tenders from the outset with realistic freight clauses and strategic buffer stocks.

At E-Station, we monitor the chokepoints, the tanker fleets and the shifting logistics routes so that your projects stay on course, however rough the seas. Discover our approach to bitumen trading and supply and our documentary logistics and Incoterms.

Secure your supply

Let’s secure your next supply cycle before the next freight spike weighs on your road budget.

Discover our sourcing and logistics solutions

Frequently asked questions about freight and bitumen prices

Why does maritime freight influence bitumen prices so much?

Bitumen travels on the same specialised tankers as crude oil and is subject to the same war-risk premiums and maritime queues, so freight costs weigh directly on its final price.

What effect did the tightening of the Strait of Hormuz have on bitumen?

Tanker freight rates in the Middle East reached twenty-year highs, causing the cost of laying asphalt to surge within weeks.

Does bitumen represent a significant share of a barrel of crude?

No, petroleum bitumen accounts for only a fraction of a barrel, but it depends entirely on the same global logistics chain as crude oil.

Why are infrastructure projects vulnerable to these tensions?

Because bitumen costs are no longer determined solely at the refinery: they now directly reflect tensions in maritime freight and global oil logistics.

How can the impact of freight on a road project's budget be anticipated?

Support from a specialised broker makes it possible to track freight rate trends and secure bitumen supplies before these tensions affect the project's budget.

Bitumen shortage: how the Hormuz crisis is driving up prices and halting construction sites

Achat bitume
Chantier de construction routière avec rouleau compresseur, illustration de la pénurie de bitume
Road construction.

Every major construction season, damaged roads and potholes resurface. This year, the bitumen shortage has a more distant cause: thousands of kilometers away, in the tense waters of the Strait ofHormuz. Disrupted shipping routes and the regional geopolitical crisis have triggered an unprecedented bitumen shortage, a key raw material for road construction. The result: soaring prices, stalled construction sites, and growing concern among industrial buyers. Here's a closer look.

Bitumen, also known as asphalt, is the petroleum-based binder that binds together the aggregates used in road construction. Its availability depends heavily on Middle Eastern refineries. When tensions rise around Hormuz, the entire chain of oil derivatives tightens, all the way down to the asphalt mix on a country road.

The effects of the crisis on construction sites

The current bitumen shortage does not originate at the plants. Several factors combine to explain this sudden shortage:

  • A strong dependence on Middle Eastern refineries (Iraq, the Emirates, Iran, Oman, Bahrain);
  • High-grade bitumen produced from very specific crude varieties that are difficult to substitute;
  • Disrupted shipping routes and imports in free fall this spring.

While buyers of crude oil have been able, to some extent, to diversify their sources, the same flexibility does not exist for bitumen. Alternatives, such as Russian crude, produce a lower-quality binder, often unsuitable for demanding projects without additional treatment.

Bitumen shortage: prices doubling, construction sites at a standstill

As supply tightened, prices have soared : in several markets, the ton of high-grade bitumen doubled compared with pre-crisis levels. For public works companies, the bill per kilogram jumped well above the reference rates on which contracts already signed are based.

The timing could not have been worse. Road maintenance and resurfacing are planned ahead of the rainy season. This year, many local authorities found themselves unable to proceed, for lack of a binder that had become both scarce and prohibitively expensive. Routine maintenance, rural connectivity projects, tourist routes: everywhere, work came to a standstill.

The public authorities' response: targeted support

Recognizing that the situation stems from exceptional international events rather than ordinary fluctuations, several authorities have approved compensation schemes to offset the extra cost of bitumen on contracts already underway. These mechanisms remain strictly regulated, however: compensation covers only the bitumen component, for clearly defined periods, and treats the crisis as a case of force majeure.

Key takeaway: security of bitumen supply depends not only on the volumes produced, but also on the reliability of transport routes and the diversification of sources. A price revision clause protects buyers and suppliers against volatility.

Secure your bitumen supply with E-Station

Beyond the specific case of bitumen, this episode illustrates a reality well known to buyers of energy commodities: a localized geopolitical shock can ripple far down the value chain. Reducing dependence on a single region, diversifying sources, and securing firm volumes are all effective levers for cushioning these shocks. Platts assessments and Reuters wire reports remain the go-to references for tracking how flows evolve.

E-Station supports industrial buyers and local authorities in sourcing bitumen and derived petroleum products, with a keen understanding of logistics routes and market dynamics. Our trading teams draw on an international network of refineries and terminals to guarantee firm volumes and structure contracts tailored to your risk exposure.

Want to secure your bitumen supply against geopolitical uncertainty? Contact our trading team for a firm quote.

On the same topic:

Frequently asked questions about the bitumen shortage

Why does the Strait of Hormuz influence bitumen availability?

Bitumen availability depends heavily on Middle Eastern refineries. When tensions rise around Hormuz, the entire chain of oil derivatives tightens, all the way down to road asphalt.

What is bitumen and why is it essential to road construction?

Bitumen, also known as asphalt, is the petroleum-based binder that holds together the aggregates used in road construction. Without a reliable supply, projects cannot move forward.

What were the consequences of the Hormuz crisis for construction projects?

Soaring prices, stalled construction sites, and growing concern among industrial buyers facing an unprecedented bitumen shortage.

Is this bitumen shortage a one-off event?

It mainly highlights the bitumen market's structural dependence on regional geopolitical tensions, a risk that can recur as long as these shipping routes remain sensitive.

How can buyers protect themselves against these shortages?

By working with a broker who diversifies supply sources and anticipates geopolitical tensions, it is possible to secure bitumen volumes even during a crisis.

Brent and WTI pull back: what the drop in crude prices means for your purchases

Plateformes pétrolières en mer illustrant la baisse des cours du brut
Prix du brut en repli : plateformes pétrolières en mer illustrant les cotations Brent et WTI

Crude oil prices are pulling back sharply. Oil prices are declining: Brent and WTI are trading around 68 dollars a barrel, weighed down by doubts over global demand and ample supply. A lull that opens a window of opportunity for buyers. Here's a closer look.

After several months of volatility tied to geopolitical tensions, crude prices are easing. This decline, driven by a combination of economic and logistical factors, is reshaping supply prospects for energy professionals.

Why crude oil prices are pulling back

Several factors are converging to explain this easing in Brent and WTI prices:

  • Persistent concerns about a slowdown in global demand;
  • Production kept at a high level by the leading exporting countries;
  • A relative easing of the tensions that had driven prices up.

Brent vs. WTI: what's the difference for your purchases?

Brent, the North Sea crude benchmark, and WTI, the North American index, often move in tandem but with a price spread that reflects regional logistical realities. Tracking both indices helps refine a buying strategy based on supply regions.

A favourable time to buy

For buyers, a price decline is often a chance to secure volumes on favorable terms. But in such a fast-moving market, timing is critical: anticipating price movements and relying on rigorous market monitoring make all the difference.

Key takeaway: Brent and WTI are pulling back to around $68, weighed down by demand doubts and ample supply. An opportunity for buyers who know how to seize the right moment.

Secure your crude oil purchases at the right time

Making the most of market dips takes responsiveness and expertise. We support professionals in their purchases of crude oil and refined products, with dedicated market monitoring. Contact our experts to optimize your supply strategy.

Crude oil prices in decline: how to take advantage of it for your purchases

A simultaneous pullback in Brent and WTI lowers the crude oil price benchmark crude oil price and passes through, with a lag, to refined products: fuels, heating oil, bitumen. For the buyer, it is an opportunity to secure volumes on favorable terms. Yet one must distinguish an underlying trend from a mere bout of weakness: inventory levels, OPEC+ decisions, global demand and geopolitical premiums shape the trajectory. Analysis from Reuters and quotations from Platts help read these signals.

Faced with a pullback in crude oil prices, savvy buyers combine opportunistic spot purchases and forward contracts to lock in an attractive average price. The market structure (contango or backwardation) guides this choice and determines the value of a long hedge.

Take advantage of falling prices with E-Station

Our trading teams continuously monitor crude oil and refined product prices to help their clients buy at the best moment. We structure spot or forward contracts and secure your volumes at the best differential.

Want to take advantage of a pullback in crude oil prices? Contact our trading team for a firm quote.

For an industrial buyer, a downward-trending crude oil price opens a rare negotiating window: it's the moment to lock in volumes, spread out purchases, and renegotiate freight clauses. The correlation between crude oil prices and those of refined products — including bitumen — remains strong, but it plays out with a lag. Anticipating this lag, rather than being subject to it, makes it possible to turn volatility into a competitive advantage across the entire purchasing campaign.

Frequently asked questions about the drop in crude oil prices

Why are Brent and WTI prices falling?

This easing is explained by persistent concerns over slowing global demand, production being kept at high levels by major exporters, and a relative easing of geopolitical tensions.

What levels are Brent and WTI currently trading at?

Prices are trading around 68 dollars per barrel, a sharp pullback after several months of volatility linked to geopolitical tensions.

Is this price drop an opportunity for buyers?

Yes, this lull opens a window of opportunity for oil product buyers, who can secure volumes on more favourable terms.

Is this price decline sustainable?

It depends on how global demand evolves and on exporters' production discipline; these balances can shift quickly depending on the geopolitical context.

How can a buyer take advantage of this price pullback?

By relying on a broker who monitors the markets continuously, it becomes possible to secure purchases at the right time and structure supply arrangements before any potential price reversal.